Bombay HC tells GST: films are not software
The court set aside proceedings involving a disputed ₹79.72 crore tax amount, plus interest and penalty, against Dharma Productions and Dharmatic Entertainment.
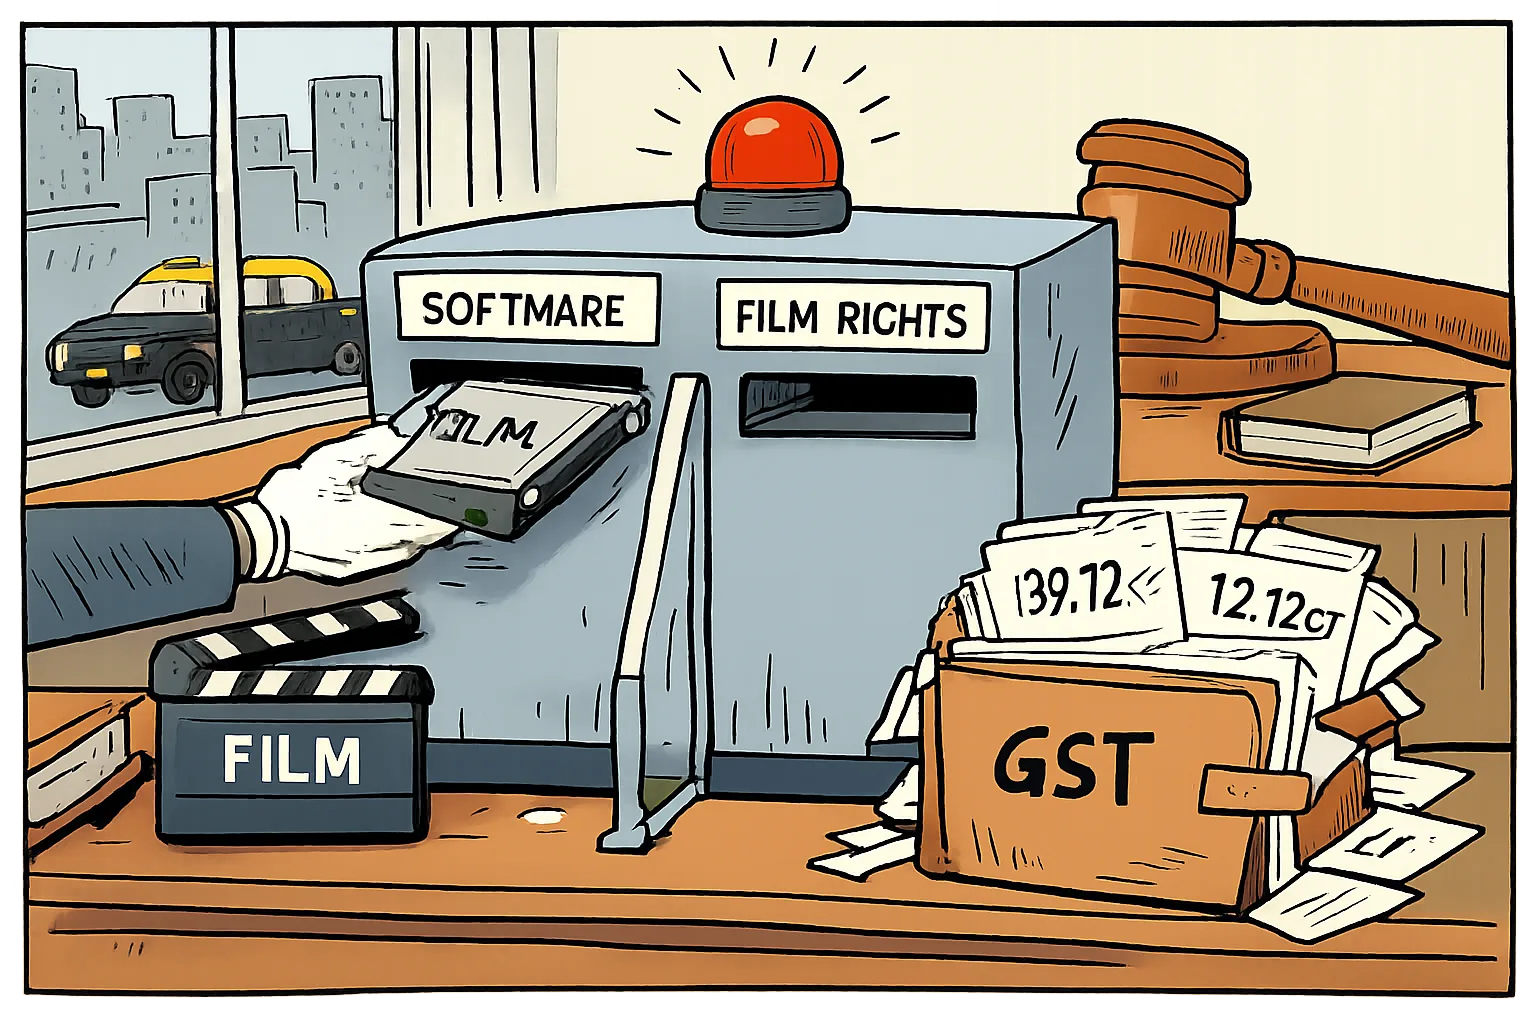
The Bombay High Court rejected the classification of digitally delivered films as software for GST purposes.
The Bombay High Court has set aside tax proceedings involving a disputed ₹79.72 crore GST amount against Dharma Productions and Dharmatic Entertainment. The figure is the tax amount recorded in the judgment; interest and penalty were separate. A smaller demand table in the same record lists ₹12.12 crore, so the court paperwork comes with its own accounting subplot.
The case covered 2017–18 to 2020–21, before the relevant GST rates were harmonised in October 2021. Maharashtra tax authorities argued that films delivered through secure digital links or hard drives should be treated as information-technology software and taxed at 18%, rather than as film-rights licensing taxed at 12%.
A division bench of Justices M. S. Karnik and Sandesh D. Patil rejected that logic on 10 September 2026. “Equating ‘digital content’ with ‘software’,” it said, had no statutory basis. The court held that classification depended on the nature of the supply, not whether delivery arrived electronically or on a hard disk. It was not a blanket ruling on every OTT transaction, and no appeal or stay was located in the material checked.